Financing a vehicle is one of the most common yet financially consequential credit commitments an individual or family will make. With automobile prices reaching historic highs and dealership financing departments offering complex combinations of promotional APRs, extended loan durations, and dealer doc fees, walking into a showroom unprepared can cost you thousands of dollars in avoidable interest. By deploying our interactive Auto Loan Calculator, car buyers can evaluate their exact monthly installments, quantify the financial benefit of trade-in equity, and compare bank pre-approvals against dealership financing with total mathematical confidence.
Whether you are purchasing a brand-new electric commuter, a dependable certified pre-owned family SUV, or exploring long-haul recreation with our companion RV Loan Calculator, mastering the fundamentals of installment loan amortization protects your household cash flow. Furthermore, understanding the interplay between secured auto loans and broader residential liabilities—such as those explored in our Mortgage Refinance and Extra Payment Guide—ensures your overall debt-to-income ratio remains balanced.
What Is an Auto Loan Calculator and Why Must You Use One Before Visiting a Dealer?
An Auto Loan Calculator is a specialized financial simulation engine that calculates the true amortized cost of an automotive installment note. When negotiation at a dealership occurs around “monthly payments” rather than out-the-door vehicle price, sales representatives frequently stretch loan terms from 48 months to 72 or 84 months to make an overpriced car appear affordable.
According to consumer automotive guidance from the Consumer Financial Protection Bureau (CFPB Auto Loan Toolkit), focusing exclusively on monthly payments while ignoring the total interest outlay is the leading cause of “negative equity” (being underwater on an automobile loan). An online calculator breaks down four essential components of vehicle financing:
- Principal Vehicle Balance: The negotiated purchase price minus cash down payment, manufacturer rebates, and net trade-in equity.
- Annual Percentage Rate (APR): The true annual interest rate charged by the lender, encompassing administrative origination charges.
- Loan Term Duration: The total length of the repayment window (typically 36, 48, 60, or 72 months).
- Total Finance Charges: The cumulative dollar sum of all interest paid to the lender across the lifespan of the loan.
The Mathematics of Auto Loan Amortization and Payment Formulas
Our online calculation engine leverages the standard fixed-installment loan amortization equation:
Monthly Payment (PMT) = P × [ r(1 + r)^n ] / [ (1 + r)^n – 1 ]
Where:
- P: Net Financed Principal Amount (Vehicle Price + Sales Tax + Fees – Down Payment – Trade-in Value).
- r: Periodic monthly interest rate (Quoted Annual Percentage Rate divided by 12).
- n: Total number of monthly installments (e.g., 60 for a 5-year loan).
Practical Calculation: The Cost of Extending Loan Terms
Consider a buyer financing a $35,000 vehicle balance at a 6.5% APR. Notice how extending the loan term slashes the monthly payment but causes total interest expenses to explode:
| Loan Term | Monthly Payment | Total Interest Paid | Total Out-of-Pocket Cost |
|---|---|---|---|
| 36 Months (3 Years) | $1,072.76 | $3,619.36 | $38,619.36 |
| 48 Months (4 Years) | $829.84 | $4,832.32 | $39,832.32 |
| 60 Months (5 Years) | $684.87 | $6,092.20 | $41,092.20 |
| 72 Months (6 Years) | $588.66 | $7,383.52 | $42,383.52 |
| 84 Months (7 Years) | $520.25 | $8,701.00 | $43,701.00 |
As demonstrated in our Auto Loan Calculator, stretching the loan from 36 months to 84 months increases your total interest bill by more than $5,080! That is deadweight capital that could otherwise fund retirement accounts or property equity.
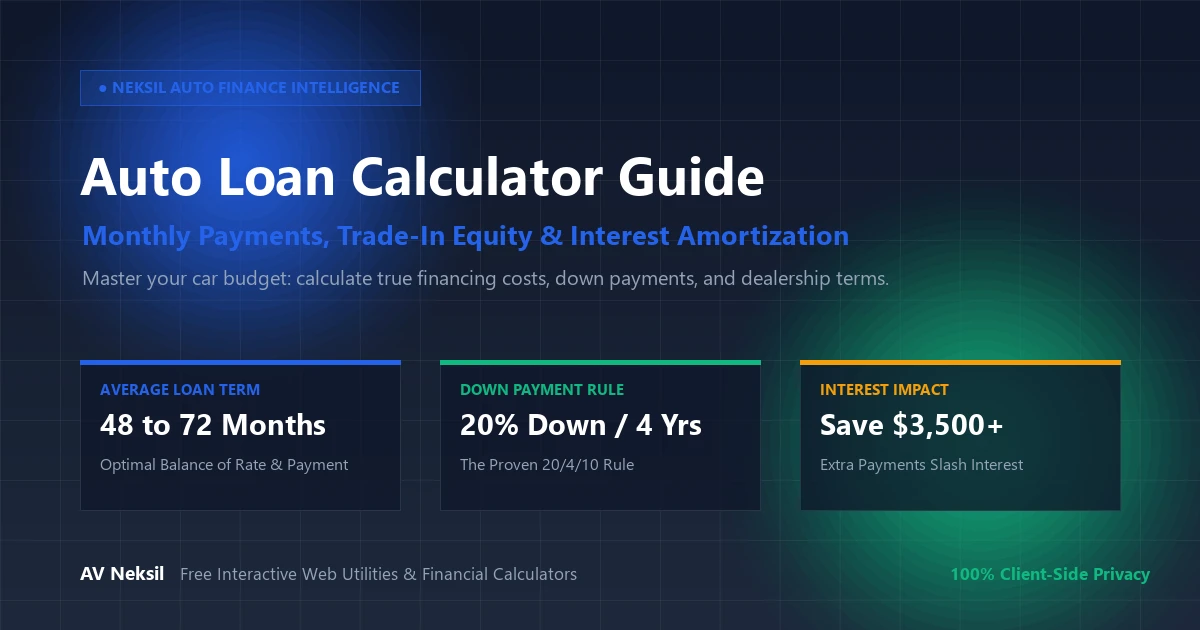
The Golden 20/4/10 Rule for Smart Car Buying
Financial planners recommend adhering to the proven 20/4/10 budgeting framework to avoid over-leveraging on automobile debt:
- Put Down at Least 20%: Making a minimum 20% down payment (via cash, trade-in, or rebates) ensures you absorb the steep first-year vehicle depreciation out-of-pocket, preventing you from becoming upside-down on the loan.
- Cap Loan Term at 4 Years (48 Months): Keeping your loan duration to a maximum of 48 months accelerates equity building, lowers the lender’s interest rate, and ensures your vehicle note is completely retired before major mechanical warranties expire.
- Keep Total Vehicle Costs Under 10% of Gross Income: Your total monthly automotive outlay—including loan principal, interest, comprehensive auto insurance, and fuel/maintenance—should never exceed 10% of your pre-tax monthly income.
How to Deal with Negative Equity and Trade-Ins
If you owe more on your existing car than a dealer offers on trade-in, you possess negative equity. Dealerships often offer to “roll” that negative balance into your new loan. For example, if your trade-in is worth $10,000 but you owe $13,000, the remaining $3,000 deficit is added directly to your new vehicle balance.
Warning: Rolling negative equity into a new car loan is extremely risky. You begin your new loan immediately underwater, requiring gap insurance to prevent catastrophic financial loss in the event of an accident. Whenever possible, pay off negative equity with cash or keep your existing vehicle until the loan reaches parity.
Step-by-Step Guide: How to Calculate Your Auto Loan on Neksil
Modeling your car loan takes less than 60 seconds with our free tool:
- Access the Tool: Open the free Auto Loan Calculator on Neksil.
- Enter Purchase Price: Input the negotiated sticker price of the car (including any estimated documentation and dealer fees).
- Input Down Payment and Trade-In: Specify your cash down payment and the net allowance for your trade-in vehicle.
- Set Interest Rate and Loan Duration: Enter your pre-approved interest rate and select your target loan term in months.
- Review Results and Amortization: Instantly view your monthly payment, cumulative interest, and export the complete repayment schedule to review with your credit union or dealership.
Frequently Asked Questions (FAQ)
Common questions from car buyers regarding auto financing and interest rates:
Should I get pre-approved before going to the dealership?
Yes, absolutely. Securing a pre-approval from a local credit union or bank gives you a competitive interest rate baseline. If the dealer wants to finance the vehicle, they must beat your pre-approved rate, saving you money.
Is it better to take dealer cash rebates or 0% APR financing?
It depends on the loan size and rebate value. On large balances, 0% APR typically saves more than a $1,500 rebate. On smaller balances, taking a $3,000 cash rebate and financing through an outside credit union at 4.5% often results in a lower total net outlay. Run both scenarios through our Auto Loan Calculator to verify which yields the lowest total expense.
Is the Neksil Auto Loan Calculator free and private?
Yes. The Neksil Auto Loan Calculator runs 100% in your browser. No social security numbers, credit pulls, or contact info are ever requested.
Conclusion: Drive Away with the Best Financial Terms
Walking into a car dealership without running your numbers is like taking an open-book exam without studying. By calculating your exact payment boundaries, interest expenses, and down payment targets beforehand, you maintain total control over your negotiations. Visit our free Auto Loan Calculator today to model your vehicle budget and drive away with confidence.